The answer to what is a debt service coverage ratio is one number: net operating income divided by total annual debt service. A result of 1.0 means income exactly covers the year's loan payments, and many lenders look for about 1.25 or higher before approving a loan.
What is a debt service coverage ratio, in plain terms #
A debt service coverage ratio, or DSCR, answers one question for a lender: does the business produce enough cash to pay its debts? It compares the cash a business generates with the payments it owes over a year. The higher the ratio, the more room there is between income and payments.
Lenders rely on it because it tests repayment directly. A business can have strong sales and still struggle if loan payments consume most of its cash. The ratio shows that gap in one figure, so applicants of very different size can be compared on the same basis.
The ratio is not a credit score, and it is not a profit margin. It looks only at cash available for debt payments.
The formula, step by step #
Start with net operating income: the cash a business earns from running its operations, before loan payments and income taxes. Lenders often begin with EBITDA or a similar cash measure, then adjust for items such as owner pay and one-time costs. Adjustments differ by lender, so ask which version a lender uses.
Next, add up total annual debt service: every principal and interest payment due in the next twelve months on all business debt, including the new loan you are requesting.
Then divide:
DSCR = net operating income ÷ total annual debt service
Read the result this way. Above 1.0, income covers payments with cash left over. At 1.0, it covers them exactly, with nothing to spare. Below 1.0, the business would need savings, owner money or new borrowing to make its payments.
A worked example with illustrative numbers #
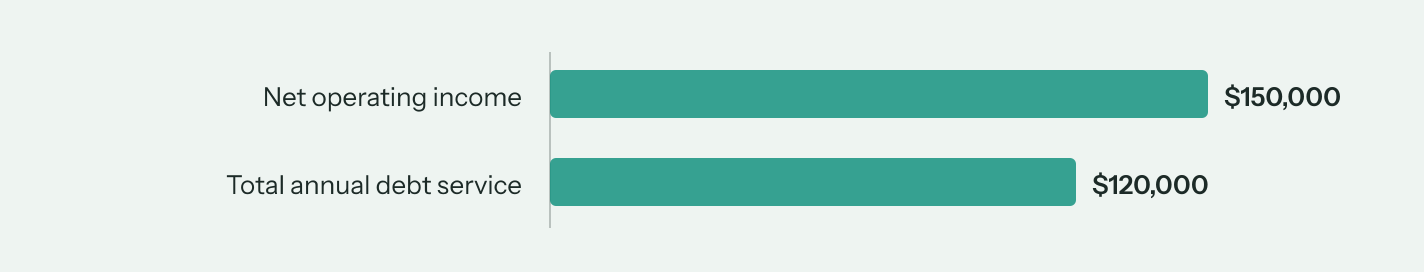
Suppose a business reports net operating income of $150,000 for the year. Its existing loans, together with the proposed new loan, require $120,000 in payments over twelve months.
$150,000 ÷ $120,000 = 1.25
The ratio is 1.25. Income is 25% larger than the payments it must cover. Now suppose the owner asks for a loan that adds $30,000 a year in payments. Total debt service rises to $150,000, and the ratio falls to 1.0. The same business is now covering its debts exactly, with no cushion for a slow month.
What counts as a good debt service coverage ratio #
Many lenders look for a ratio of about 1.25 or higher before approving a loan. That is a rule of thumb, not a legal cutoff. Each lender sets its own floor, and the bar moves with the loan type, the collateral offered, the owner's credit and the stability of the business's income. A borderline ratio can still be approved with a larger down payment or a personal guarantee. A strong ratio can be declined if cash flow swings widely.
A ratio below 1.0 means current cash does not cover payments. Lenders usually want a clear reason and a concrete plan before they consider it. Several years of steady ratios usually count for more than one good year.
How lenders use DSCR, and how it differs by loan type #
Lenders use DSCR as one test among several. They also review credit history, time in business, collateral and the purpose of the loan. The Federal Reserve's Small Business Credit Survey follows how frequently small companies seek funding, how frequently they receive it, and where they turn for it. Its 2026 employer-firm report is a useful reference on debt and financing outcomes.
Loan type changes the test. A bank term loan usually requires a documented DSCR from financial statements and tax returns. An SBA 7(a) loans is made by a private lender but partly guaranteed by the U.S. Small Business Administration, and the lender still underwrites cash flow. A line of credit is often judged on the business's revenue pattern and its ability to carry a balance. A merchant cash advance and revenue-based financing are repaid from a share of sales or revenue, so the more useful question is how much of that revenue the payments take.
Costs and speed by funding type #
Costs are shown the way each option is usually quoted. Speed and requirements vary by lender.
| Option | Typical cost | Speed | What it needs |
|---|---|---|---|
| Bank term loan | Interest rate set by the lender; compare APRs | Often several weeks | Financial statements, tax returns, a documented DSCR, usually collateral or a guarantee |
| SBA 7(a) loans | Rates capped by SBA rules, plus any SBA guarantee fee | Usually slower, since the lender and SBA both review | Eligibility under SBA size standards, a solid DSCR, owner personal guarantees in most cases |
| Credit lines for businesses | Interest on the amount drawn; fees may apply | Setup can take weeks; draws are fast once open | Revenue history, credit review, sometimes collateral |
| Merchant cash advance | Factor rate: for example, 1.25 factor over 8 months ≈ 65–75% APR | Often within days | Steady card sales or bank deposits, and a recent statement history |
| Revenue-based financing | Fixed fee repaid as a share of revenue; ask for the APR-equivalent | Often within days | Consistent revenue and clean bank records |
A factor rate works as a flat multiplier on the amount funded, not as an annual rate. A 1.25 factor means the business repays $1.25 for every $1 funded, and the length of repayment determines what that costs per year. Over eight months, that works out to roughly 65–75% APR, which is why the APR-equivalent belongs next to any factor rate. California and New York now require commercial financing disclosures that state a total dollar cost and an annualized rate, so offers can be compared.
Ways to improve a low ratio #
A ratio has two levers: raise net operating income or lower total annual debt service.
- Raise income. Adjust prices where demand allows, cut operating costs that do not affect sales, and collect receivables faster.
- Lower debt service. Refinancing or extending a term can reduce annual payments, though total interest may rise. Paying down a short-term balance or closing unused credit lines can also help.
- Clean up the books. Lenders can only credit income they can verify. The SBA's free guidance on bookkeeping, cash flow and financial statements is a practical place to start.
- Time the request. Applying after a strong quarter tends to produce a better picture than applying during a dip.
Adding new debt lowers the ratio. Some owners take a smaller loan first, then return once income has grown.
Is a DSCR of 1.0 enough to get a loan? #
Sometimes, but rarely on its own. A 1.0 ratio means income exactly matches payments, so any drop in sales leaves the business short. Lenders that approve at that level usually want collateral, a personal guarantee, a clear reason the next year will be stronger, or a smaller loan. A ratio of 1.25 or higher gives a lender more comfort and gives you more room to negotiate terms.
What is a good debt service coverage ratio? #
For most business loans, lenders look for about 1.25 or higher. A ratio of 1.0 or above means income covers payments, but with little room for a slow month. Some lenders accept lower ratios when the loan is well secured or the owner's credit is strong, and others require more for riskier businesses. Ask each lender what it targets, since the answer varies by lender and by loan.
How does DSCR differ from a debt-to-income ratio? #
A debt-to-income ratio compares a person's monthly debt payments with monthly income, and it is most common in personal and mortgage lending. DSCR compares a business's operating cash flow with the payments that business owes. It asks whether the business can pay its own debts, not whether a person can carry them. Both are payment-to-income tests, but they measure different borrowers.
Does DSCR only matter for real estate loans? #
No. DSCR is most familiar in commercial real estate lending, where property income is weighed against the mortgage payment. It is also used for business term loans, SBA loans and other credit a business repays from operating cash. Products repaid from a share of sales, such as merchant cash advances and revenue-based financing, are judged differently, because payments rise and fall with revenue.
How do I calculate debt service coverage ratio in Excel? #
Put net operating income in one cell and total annual debt service in another. In a third cell, divide the first by the second. Format the result with two decimal places, so 1.25 displays clearly. If you have several years of figures, use one row per year to see the trend. Keep the debt service column to principal and interest for the next twelve months, and include any new loan you are considering.
Matching the funding to the cash you can show #
A bank term loan or SBA 7(a) loans fits a business with two or more years of financial statements, a DSCR at or above about 1.25, and a purpose that pays back over several years, such as equipment or a planned expansion. A line of credit fits seasonal swings in cash. A merchant cash advance or revenue-based financing can suit a short-term need with a clear payoff, when a bank cannot move quickly enough and the owner has reviewed the total cost. These products are a poor fit for long-term needs or thin margins, because payments take a share of sales every day or week.
If your ratio is comfortably above 1.0 and your statements are current, a bank or SBA lender is usually the lower-cost route. If you need money in days and understand what it costs, a faster product may fit.
Next step: if you know your net operating income and annual debt payments, start your request, and we will lay out the cost of each option side by side.
Sources #
This explainer is general information, not advice for your situation. Nothing applies to you except the terms written in an agreement you sign. How this site is paid.